Table of Contents
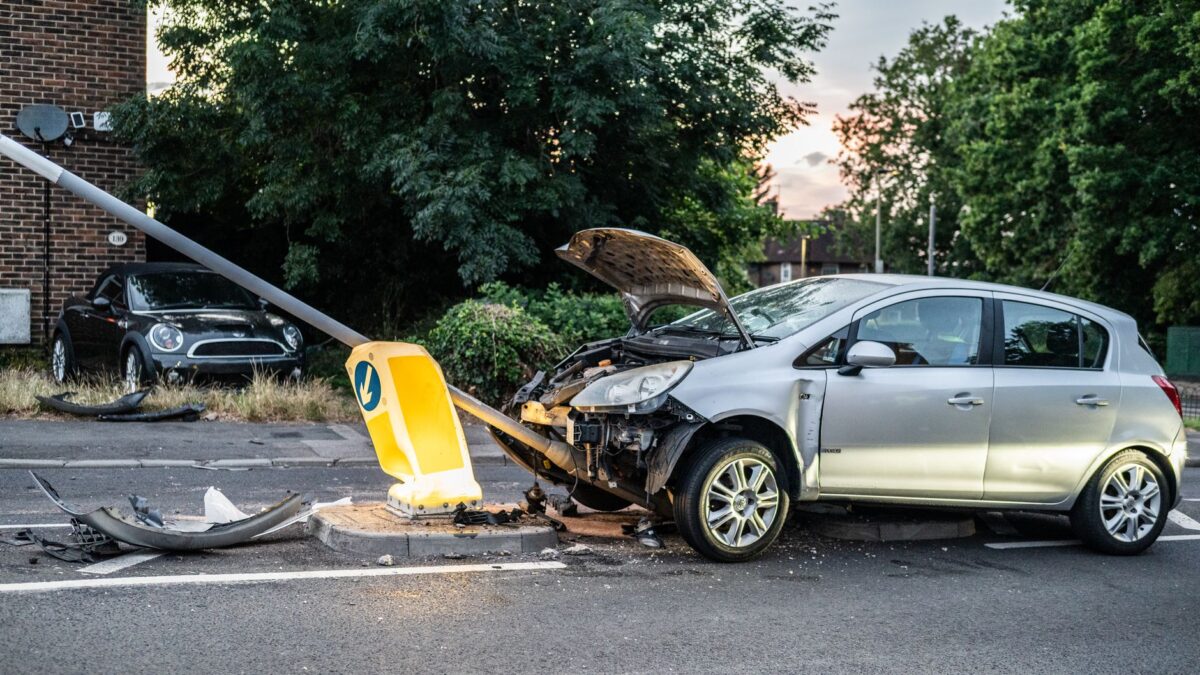
A total loss car is a vehicle that your insurer has decided is not worth fixing. This usually happens when repairs would cost close to or more than the car is worth. Total losses are now more common than ever. CCC Intelligent Solutions’ Crash Course 2026 report found that 23.
1% of claims in 2025 ended in a total loss, the highest share on record. Repair costs keep rising, and modern cars carry expensive sensors and cameras. As a result, even moderate crashes can now total a vehicle. Knowing how a total loss car is decided helps you protect your payout. It also helps you push back when an offer seems too low.
What Makes a Total Loss Car Under Insurance Rules
An insurer declares a total loss when fixing the car makes no financial sense. The key number is the vehicle’s actual cash value (ACV). ACV is what your car was worth just before the accident. It reflects age, mileage, condition, trim level, and local market prices. It is not what you paid for the car or what you still owe on it.
A car can be totaled in several situations. A severe collision is the most common cause. However, flood damage, fire, hail, and theft can also lead to a total loss. For example, a stolen car that is not recovered within a set period, often 30 days, is typically paid out as a total loss. Flood damage is another frequent cause, because water can ruin electrical systems and airbags.
Coverage matters too. A total loss car is only paid by your own insurer if you carry collision or comprehensive coverage. Collision pays for crash damage. Comprehensive covers theft, weather, fire, and animal strikes. If another driver caused the crash, their liability coverage pays instead. If you carry only liability coverage and you caused the crash, you typically get nothing for your own vehicle.
How Insurers Decide: Thresholds and the Total Loss Formula
Each state sets its own rules for when a vehicle must be totaled. There are two main methods. The first is a fixed percentage threshold. The second is the total loss formula, often called the TLF. Roughly 30 states use a fixed percentage. Around 20 states use the formula instead.
Under a percentage threshold, the car is totaled once repair costs reach a set share of its ACV. Most of these states land between 70% and 80%. For example, if your state uses 75% and your car is worth $20,000, repairs of $15,000 or more make it a total loss car. Some states set the bar higher. Colorado and Texas use 100% of ACV, while Florida uses 80%. Iowa sits on the low end at 50%.
The total loss formula works differently. The insurer adds the repair cost to the salvage value. If that sum equals or exceeds the ACV, the car is totaled. States such as California, Georgia, Illinois, Ohio, Pennsylvania, and Washington use this approach. Salvage value is what the damaged car would sell for at auction.
| Method | How It Works | Example ($20,000 ACV) |
|---|---|---|
| 75% threshold | Repairs ≥ 75% of ACV | Totaled at $15,000 in repairs |
| 80% threshold (e.g., Florida) | Repairs ≥ 80% of ACV | Totaled at $16,000 in repairs |
| 100% threshold (e.g., Texas) | Repairs ≥ full ACV | Totaled at $20,000 in repairs |
| Total loss formula | Repairs + salvage ≥ ACV | $14,000 repairs + $6,000 salvage = totaled |
Thresholds also change over time. Rhode Island raised its threshold from 75% to 80% in 2025. In 2026, lawmakers there sent a bill to the governor that would raise it to 85%. South Dakota has weighed a fixed 75% rule. Check your state insurance department for the current number.
Keep in mind that thresholds are a minimum, not a ceiling. In most cases, an insurer may total a car below the state threshold if repairs are not cost-effective. Hidden damage often appears once a shop takes the car apart. As a result, a car that first looked repairable can become a total loss car after the full inspection.
How Your Total Loss Payout Is Calculated
Once your vehicle is totaled, the insurer pays its ACV minus your deductible. For example, a car valued at $18,000 with a $1,000 deductible produces a $17,000 check. If you have a loan, the lender is paid first. You receive whatever remains.
Insurers typically use valuation services to set ACV. These tools pull recent sales of similar vehicles in your area. They then adjust for mileage, options, and condition. However, these reports can contain errors. A wrong trim level or missed option can lower your offer by hundreds or thousands of dollars.
Many states also require insurers to cover sales tax and title and registration fees on a total loss. Rules vary, so ask your adjuster directly. Payment timelines also vary by state. Many states require insurers to settle within roughly 30 days after the claim is fully documented.
Owing more than the car is worth creates a problem. This is called being “upside down” on a loan. Gap insurance pays the difference between the ACV and your loan balance. Without it, you could owe thousands on a car you no longer have. New cars lose value quickly, so gap coverage matters most in the first few years of a loan.
What to Do If Your Vehicle Is a Total Loss Car
First, request a copy of the full valuation report. Review every detail, including mileage, trim, and listed options. Then compare the comparable vehicles the insurer used. Make sure they match your car’s year, model, and condition.
Second, gather your own evidence. Collect local listings for similar cars. Save receipts for recent upgrades, such as new tires, a new battery, or major repairs. Typically, documented improvements can raise your car’s value. Send this information to your adjuster in writing.
📋 Get Free Insurance Guides
Free · No spam · Unsubscribe anytime
Third, know your dispute options. Many auto policies include an appraisal clause. Under this clause, you and the insurer each hire an independent appraiser. If they disagree, a neutral umpire makes the final call. You usually pay for your own appraiser, often $200 to $500. However, the extra payout can easily exceed that cost.
Fourth, consider whether to keep the car. In many states, you can retain a total loss car. The insurer then subtracts its salvage value from your payout. The vehicle will receive a salvage title. It must typically pass a state inspection before it gets a rebuilt title and can be driven again. Rebuilt-title cars are often harder to insure and resell.
Finally, if negotiations stall, file a complaint with your state insurance department. Regulators track unfair claim practices. In most cases, a complaint prompts a closer review of your file. You can also consult an attorney or public adjuster for high-value disputes.
Also, remove your personal items and license plates before the car is towed to auction. Cancel or transfer your coverage once the claim is settled. As a result, you avoid paying premiums on a vehicle you no longer own.
Frequently Asked Questions
Can I negotiate the payout on a total loss car?
Yes. Insurers expect some negotiation on valuations. For example, showing local listings for similar cars or proof of recent upgrades can raise your offer. If talks fail, you can typically invoke your policy’s appraisal clause.
Will a total loss car raise my insurance rates?
It depends on who caused the accident. In most cases, an at-fault crash raises your premium regardless of whether the car was totaled. However, comprehensive claims like hail or theft usually have a smaller effect on rates.
What happens if I owe more on my loan than the car is worth?
The insurer pays the ACV, not your loan balance. As a result, you must cover any shortfall unless you have gap insurance. Gap coverage pays the difference between the payout and the remaining loan amount.
How long does a total loss car claim take?
Typically, a total loss claim takes two to six weeks. Many states require payment within about 30 days once paperwork is complete. Delays usually come from title transfers, lender payoffs, or valuation disputes.
Compare Insurance Rates
Ready to see if you could be paying less? Compare quotes from top insurers in your area. Getting multiple quotes is the most effective way to find a better rate.
(paid link)
Official Sources & Resources
For verified information on auto insurance regulations and consumer protection:
- NAIC (National Association of Insurance Commissioners): naic.org
- Insurance Information Institute: iii.org
- Federal Trade Commission — Auto Insurance: consumer.ftc.gov
- USA.gov — Car Insurance: usa.gov/car-insurance
Content last reviewed October 2026. If you notice any outdated information, please contact us.